
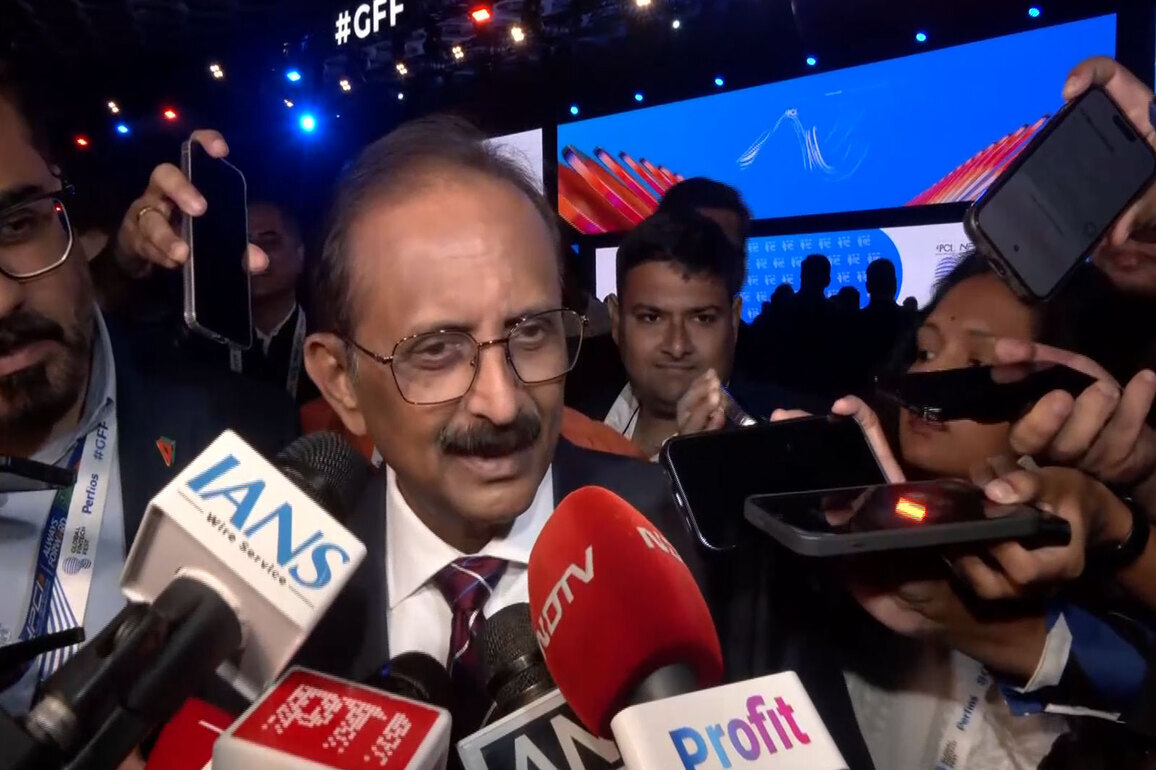
Agentic AI is moving from experimentation to real-world deployment across the financial services industry. A recent statement by State Bank of India (SBI) Chairman Challa Sreenivasulu Setty highlights how one of India’s largest banks is approaching this transition.
Speaking at the Global Fintech Fest 2026, Setty identified three key areas where SBI plans to focus its agentic AI adoption: customer engagement, employee productivity, and proactive risk management.
The announcement reflects a broader shift in enterprise AI. Traditional AI systems typically assist employees by generating recommendations, insights, or responses. Agentic AI goes a step further by enabling systems to coordinate tasks, respond to changing circumstances, and potentially take actions with a defined level of autonomy.
1. Hyper-Personalised Customer Engagement
The first priority for SBI is improving customer engagement through hyper-personalisation.
Banks have access to enormous volumes of customer, transaction, product, and interaction data. Agentic AI can potentially bring this information together to understand customer needs and coordinate personalised interactions.
Instead of simply responding to a customer query, an AI agent could potentially identify the customer’s requirement, gather relevant information, recommend an appropriate service, and initiate the next step within predefined controls.
This could help banks move from reactive customer service toward more proactive engagement.
For customers, the potential benefits include:
✓ More personalised banking experiences
✓ Faster responses to requests
✓ Context-aware recommendations
✓ Reduced need to navigate multiple banking processes
✓ More consistent service across digital channels
However, personalisation at this scale requires strong data governance and clear boundaries around how customer information can be accessed and used.
2. Improving Employee Productivity
SBI’s second focus area is employee productivity and process simplification.
Banking involves numerous repetitive and interconnected processes. Employees often need to collect information from different systems, verify documents, complete compliance checks, prepare reports, and coordinate with multiple teams.
Agentic AI could help orchestrate several of these activities rather than automating just one individual task.
For example, an AI agent could support an employee by gathering relevant information, checking predefined requirements, preparing documentation, and routing the workflow to the appropriate team for approval.
The objective is not necessarily to replace employees. Instead, agentic AI can potentially reduce administrative workloads and allow employees to focus on activities requiring human judgment, relationship management, and decision-making.
This represents an important evolution from AI-assisted productivity to AI-orchestrated workflows.
3. Proactive Risk Management
The third focus area is particularly important for financial institutions: proactive risk management.
Banks operate in an environment where fraud, compliance failures, credit risk, cybersecurity threats, and operational risks can evolve rapidly.
Agentic AI could help monitor large volumes of information, identify unusual patterns, coordinate multiple risk checks, and trigger appropriate responses based on predefined policies.
Potential applications include:
✓ Fraud detection
✓ KYC and AML processes
✓ Loan appraisal and underwriting
✓ Transaction monitoring
✓ Compliance workflows
✓ Early identification of emerging risks
SBI’s broader discussion around agentic AI also highlights the potential for autonomous systems across areas such as loan appraisal, underwriting, KYC compliance, anti-money-laundering checks, and fraud detection.
From AI Recommendations to Autonomous Execution
The bigger significance of SBI’s approach is the transition from AI as a tool to AI as an operational capability.
Traditional AI may tell an employee what action to consider.
Agentic AI can potentially determine the next steps in a workflow and execute approved actions within predefined boundaries.
This distinction becomes especially important in banking.
An autonomous system operating in a financial environment cannot simply be evaluated on whether it produces a useful answer. It must also be accurate, explainable, auditable, secure, and accountable.
SBI Chairman Setty has emphasised this challenge, noting that financial institutions need to think beyond conventional AI accuracy and establish stronger mechanisms for accountability and traceability when AI moves from recommendation to execution.
Why Governance Becomes Critical for Agentic AI
Greater autonomy also creates greater responsibility.
When an AI agent is only providing a recommendation, a human can review the recommendation before acting.
When an agent is authorised to execute a transaction or initiate a workflow, the organisation needs to know:
Who authorised the agent?
What data can the agent access?
What actions can it perform?
Why did it take a particular action?
Can the action be audited or reversed?
These questions are leading financial institutions toward concepts such as “Know Your Agent” (KYA), extending the principles of KYC into an environment where AI agents may participate directly in financial processes.
The Enterprise Lesson: Agentic AI Needs More Than a Powerful Model
SBI’s strategy offers a broader lesson for enterprises exploring agentic AI.
Successful agentic AI deployment is not simply about selecting the most capable AI model. Enterprises also need the underlying data, workflows, integrations, security controls, governance mechanisms, and monitoring capabilities required to operate autonomous systems safely.
A practical enterprise agentic AI architecture may therefore require:
Data foundation → Trusted and accessible enterprise data
Context layer → Relevant business and customer context
AI agents → Systems capable of reasoning and executing defined tasks
Workflow orchestration → Coordination across applications and business processes
Governance and security → Policies, permissions, audit trails, and controls
Human oversight → Escalation and approval mechanisms for high-impact decisions
This becomes particularly important in regulated industries such as banking, healthcare, insurance, and financial services.
What SBI’s Move Signals for the Future of Banking
SBI’s three priorities—customer engagement, productivity, and risk management—represent three of the strongest enterprise use cases for agentic AI.
The customer side focuses on delivering more personalised experiences.
The employee side focuses on simplifying complex workflows.
The risk side focuses on making financial systems more proactive and resilient.
Together, these areas demonstrate how agentic AI could become part of the operating model of financial institutions rather than remaining an isolated technology experiment.
The next phase of AI adoption will therefore be less about asking “Can AI perform this task?” and more about asking “Which decisions and workflows can AI safely execute, and what controls are required?”
For enterprises, that shift—from AI assistance to governed autonomy—could define the next stage of digital transformation.
Conclusion
SBI’s approach to agentic AI provides a useful blueprint for how large financial institutions can think about autonomous AI adoption.
The focus on hyper-personalised customer engagement, employee productivity, and proactive risk management shows that agentic AI is increasingly being evaluated based on business outcomes rather than technology demonstrations.
But as AI agents gain the ability to act independently, trust, governance, security, accountability, and data quality become just as important as model performance.
The organisations that can combine intelligent agents with trusted data, strong governance, and well-defined business workflows will be better positioned to turn agentic AI from an emerging technology into a scalable enterprise capability.
